
A Chapter in My Late Start Retirement Journey
Several years into working in America, I received a letter from the Social Security Administration. It informed me that I had met the requirement for Social Security credits.
I remember reading it. I don’t remember understanding it.
At the time, it meant nothing to me — just another piece of official mail confirming some bureaucratic milestone I hadn’t been paying attention to. I set it aside and went back to whatever I was working on that day.
It wasn’t until I started taking retirement seriously that I began logging into the SSA website on my own, checking my estimated benefits every so often, using the numbers to recalibrate when I might actually be able to retire and what I’d need to get there.
The Graph That Changed the Question
The SSA login page shows a simple comparison: what your monthly benefit looks like if you claim early, at full retirement age, or if you delay.
In my case, the numbers looked like this — claim at 62, and I’d receive $1,970 a month. Wait until 67, my full retirement age, and it climbs to $3,258. Delay all the way to 70, and it reaches $4,213.
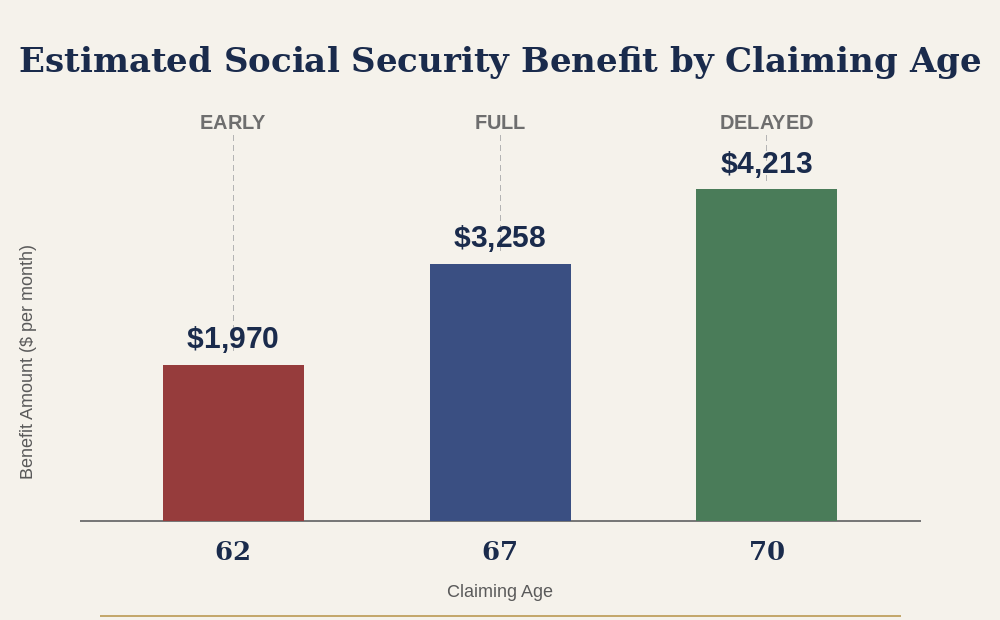
Seeing those three bars side by side changed the question I’d been asking myself. It wasn’t really “when can I retire” anymore. It was “how much of my life do I want to trade for how much monthly income” — because that’s really what the graph is showing. Every year I wait is a year of work traded for a permanently higher check.
Social Security alone isn’t enough to live on, at least not at the standard of living I’d want to keep. So the real question of when I retire doesn’t rest on Social Security by itself — it rests on how well my 401(k) and Roth IRA can cover the gap. My current plan is to have Social Security cover roughly half of my retirement income, with my retirement accounts covering the other half. Based on where those numbers currently stand, that points to 67 as the earliest point where I could retire without a real drop in the life I’m used to living.
What I Didn’t Know About My Wife’s Benefit
My wife has worked part-time, irregularly, over the years — enough that she hasn’t yet met the credit requirement for her own Social Security benefit. And even once she does, her benefit would likely be small enough that claiming 50% of mine, as a spousal benefit, would actually work out better for her.
I only learned that spousal benefits existed — that a spouse can claim up to 50% of the working spouse’s benefit — a few years ago. Not decades into working here. Not even ten years ago. A few years ago.
That’s a fairly basic piece of the system, and I went most of my adult life in this country without knowing it existed.
A Conversation That Surprised Me
Recently, I was talking about retirement with another immigrant engineer at my company. It turned out he knew even less about Social Security than I did — including the spousal benefit. He didn’t know his wife could claim half of his benefit either.
What struck me most was that he’s been in this country longer than I have, and he holds a Ph.D. earned right here in the United States. If anyone should have absorbed this information along the way, it would be someone with more years and more American education than me.
But financial literacy doesn’t seem to arrive automatically, no matter how many degrees you collect or how many years you accumulate in a place. It has to be sought out, deliberately, usually later than it should be.
I’m still doing that seeking. The graph on the SSA website is one small piece of it — three bars, three ages, and a much clearer sense than I had before of what my late start actually requires from me now.